

Raumbeispiel
169
Otto Pippel
Wirtsgarten in Berg am Starnberger See, Wohl um 1930.
Oil on canvas
Estimate:
€ 12,000 - 15,000
$ 13,440 - 16,800
169
Otto Pippel
Wirtsgarten in Berg am Starnberger See, Wohl um 1930.
Oil on canvas
Estimate:
€ 12,000 - 15,000
$ 13,440 - 16,800
Otto Pippel
1878 - 1960
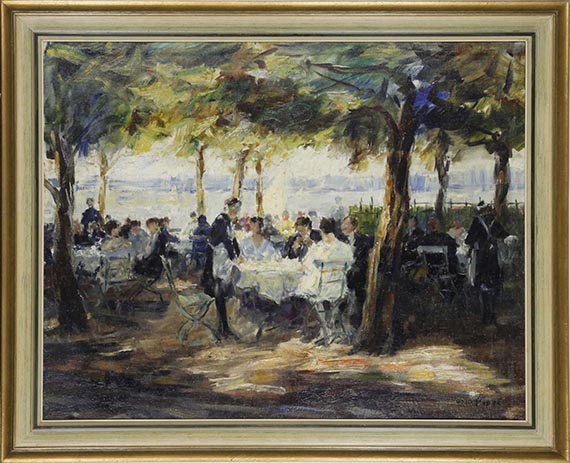
Wirtsgarten in Berg am Starnberger See. Wohl um 1930.
Oil on canvas.
Signed in the lower right. Signed, titled, and inscribed with the location “Planegg” on the reverse of the canvas. 80.5 x 100.5 cm (31.6 x 39.5 in). [AW].
• Beneath a light-filled canopy of branches overlooking Lake Starnberg, Otto Pippel brings Bavarian culture to life.
• A delicate yet vigorous painting technique in the style of German Late Impressionism.
• Pippel’s works are in, among others, the Städtische Galerie im Lenbachhaus, Munich, and the Städtische Galerie, Rosenheim.
PROVENANCE: Private collection.
Private collection in Lower Saxony (inherited from the above)
In the family’s possession ever since.
Called up: December 5, 2026 - ca. 14.32 h +/- 20 min.
1878 - 1960
Wirtsgarten in Berg am Starnberger See. Wohl um 1930.
Oil on canvas.
Signed in the lower right. Signed, titled, and inscribed with the location “Planegg” on the reverse of the canvas. 80.5 x 100.5 cm (31.6 x 39.5 in). [AW].
• Beneath a light-filled canopy of branches overlooking Lake Starnberg, Otto Pippel brings Bavarian culture to life.
• A delicate yet vigorous painting technique in the style of German Late Impressionism.
• Pippel’s works are in, among others, the Städtische Galerie im Lenbachhaus, Munich, and the Städtische Galerie, Rosenheim.
PROVENANCE: Private collection.
Private collection in Lower Saxony (inherited from the above)
In the family’s possession ever since.
Called up: December 5, 2026 - ca. 14.32 h +/- 20 min.

Buyer's premium, taxation and resale right compensation for Otto Pippel "Wirtsgarten in Berg am Starnberger See"
This lot can be purchased subject to differential or regular taxation, artist‘s resale right compensation is due.
Differential taxation:
Hammer price up to 2,000,000 €: herefrom 34 % premium.
The share of the hammer price exceeding 2,000,000 € is subject to a premium of 29 % and is added to the premium of the share of the hammer price up to 2,000,000 €.
The share of the hammer price exceeding 4,000,000 € is subject to a premium of 22 % and is added to the premium of the share of the hammer price up to 4,000,000 €.
The buyer's premium contains VAT, however, it is not shown.
Regular taxation:
Hammer price up to 2,000,000 €: herefrom 29 % premium.
The share of the hammer price exceeding 2,000,000 € is subject to a premium of 23% and is added to the premium of the share of the hammer price up to 2,000,000 €.
The share of the hammer price exceeding 4,000,000 € is subject to a premium of 15% and is added to the premium of the share of the hammer price up to 4,000,000 €.
The statutory VAT of currently 7 % is levied to the sum of hammer price and premium.
We kindly ask you to notify us before invoicing if you wish to be subject to regular taxation.
Calculation of artist‘s resale right compensation:
For works by living artists, or by artists who died less than 70 years ago, a artist‘s resale right compensation is levied in accordance with Section 26 UrhG:
4 % of hammer price from 400.00 euros up to 50,000 euros,
another 3 % of the hammer price from 50,000.01 to 200,000 euros,
another 1 % for the part of the sales proceeds from 200,000.01 to 350,000 euros,
another 0.5 % for the part of the sale proceeds from 350,000.01 to 500,000 euros and
another 0.25 % of the hammer price over 500,000 euros.
The maximum total of the resale right fee is EUR 12,500.
The artist‘s resale right compensation is VAT-exempt.
Differential taxation:
Hammer price up to 2,000,000 €: herefrom 34 % premium.
The share of the hammer price exceeding 2,000,000 € is subject to a premium of 29 % and is added to the premium of the share of the hammer price up to 2,000,000 €.
The share of the hammer price exceeding 4,000,000 € is subject to a premium of 22 % and is added to the premium of the share of the hammer price up to 4,000,000 €.
The buyer's premium contains VAT, however, it is not shown.
Regular taxation:
Hammer price up to 2,000,000 €: herefrom 29 % premium.
The share of the hammer price exceeding 2,000,000 € is subject to a premium of 23% and is added to the premium of the share of the hammer price up to 2,000,000 €.
The share of the hammer price exceeding 4,000,000 € is subject to a premium of 15% and is added to the premium of the share of the hammer price up to 4,000,000 €.
The statutory VAT of currently 7 % is levied to the sum of hammer price and premium.
We kindly ask you to notify us before invoicing if you wish to be subject to regular taxation.
Calculation of artist‘s resale right compensation:
For works by living artists, or by artists who died less than 70 years ago, a artist‘s resale right compensation is levied in accordance with Section 26 UrhG:
4 % of hammer price from 400.00 euros up to 50,000 euros,
another 3 % of the hammer price from 50,000.01 to 200,000 euros,
another 1 % for the part of the sales proceeds from 200,000.01 to 350,000 euros,
another 0.5 % for the part of the sale proceeds from 350,000.01 to 500,000 euros and
another 0.25 % of the hammer price over 500,000 euros.
The maximum total of the resale right fee is EUR 12,500.
The artist‘s resale right compensation is VAT-exempt.
Headquarters
Joseph-Wild-Str. 18
81829 Munich
Phone: +49 89 55 244-0
Fax: +49 89 55 244-177
info@kettererkunst.de
Louisa von Saucken / Undine Schleifer
Holstenwall 5
20355 Hamburg
Phone: +49 40 37 49 61-0
Fax: +49 40 37 49 61-66
infohamburg@kettererkunst.de
Dr. Simone Wiechers / Nane Schlage
Fasanenstr. 70
10719 Berlin
Phone: +49 30 88 67 53-63
Fax: +49 30 88 67 56-43
infoberlin@kettererkunst.de
Cordula Lichtenberg
Gertrudenstraße 24-28
50667 Cologne
Phone: +49 221 510 908-15
infokoeln@kettererkunst.de
Hessen
Rhineland-Palatinate
Miriam Heß
Phone: +49 62 21 58 80-038
Fax: +49 62 21 58 80-595
infoheidelberg@kettererkunst.de
We will inform you in time.